Selling Your Practice? Consider These Issues First

There has been a resurgence of practice acquisitions of late. If you are an owner in your practice, chances are you are considering selling your practice or soon will be. Other than purchase price, which is the bait on the hook, what else should you consider?

Who’s Your Buyer?

In general, there are three types of buyers. First, there are hospital buyers. With few exceptions, our recent experience has been that hospitals pay practices the fair market value of tangible assets. Often, the “value” is achieved by more lucrative employment agreements as a result of the hospital system’s reimbursement rates that are more favorable than what a private practice might negotiate. There is not a lot of money transferred at closing.

The second types of buyers are other practices. Often, acquirers have built an efficient practice, and believe that they can squeeze inefficiencies out of smaller practices and make them more profitable. These acquirers usually have methods and processes that, when shared, make the acquired practice more profitable and thus more valuable.

These acquirers may have a long range plan of building a bigger practice, which would make them more valuable to the third type of buyer, private equity backed management service organizations, or “MSOs”. While some MSOs are not backed by private equity, we will assume for the purposes of this discussion, that they are. This type of transaction involves the MSO purchasing the non-clinical assets of a practice, including goodwill. The practice owners often sell their ownership in the practice to a physician who may be “friendly” with the MSO. The friendly physician, simultaneous with the closing, causes to enter into a long term management services agreement (MSA) with the MSO. These types of transactions have become popular among practices because, well, adult money changes hands at closing. The MSO receives a return on its investment through the fees paid under the MSA. Often, these fees are paid from the reduced compensation of the providers in the practice. Further, in many of these transactions, owners in the practice are required to “roll-over” purchase price into the MSO as an investment.

What Is Your Timing?

Often, timing can dictate the type of purchaser whom you pursue. We have helped smaller practices whose founder has experienced health issues and must transition his or her practice on a short time frame. Founders often do this to transition loyal employees and to address the nightmarish administrative burden of administering patient charts of a closed practice. In those cases, hospitals or other practices may be a better fit because there is often a prior working relationship between the buyer and seller.

Donating Your Practice

Another exit strategy is for the founding physician to donate his or her practice to a non-profit hospital. With some significant caveats, a physician may be able to deduct as a charitable contribution the appraised value of his or her practice. This allows the physician to meet his or her transition goals with respect to employees and patient charts, while at the same time giving him or her significant tax advantages that may outweigh mere liquidation value of the practice.

What Are Your Goals?

If you have plenty of time to search for a buyer, then your goal is to obtain the most value for your practice. This is not only a function of purchase price, but also depends on the tax treatment of the consideration you receive. For example, if your practice is a C corporation and you sell assets, the corporation will pay tax on the gain resulting from the sale, and the C corporation’s shareholders will pay tax on the dividend they receive as a result of the sale. C corporation dividends are not deductible by the C corporation.  As a result, this phenomenon is often referred to as a “double tax” since the C corporation pays tax on the gain and the shareholders pay tax on the resulting dividend.

The goal should be to structure the transaction so that there is no double tax, that the proceeds received by the owners are taxed at what have been lower capital gains rates, and that the tax on any roll-over equity be deferred until that roll-over equity is liquidated. This is often easier said than done.

Second Bites of the Apple

As a general rule, if practices sell to private equity, they are often valued based on a multiple of “EBITDA,” which is “earnings before interest, taxes, depreciation, and amortization.” Also, as a general rule, larger practices can often command a higher multiple of EBITDA than a comparably run smaller practice. One way to think of this is that one practice with 100 providers would be more valuable than the sum of the value of 50 practices with two providers each. This matters because with practice and MSO acquirers, the selling physicians may be asked to roll-over equity into the new enterprise. The goal of course is that the new enterprise will grow and prosper, and the rolled over equity will create another liquidity event for the physicians.

Not as Easy as It Looks

The complexity of a sale is often dictated by the type of buyer. In a hospital transaction, there is usually an asset purchase agreement and employment agreements for the providers. Since hospitals are exempt from the prohibition on the corporate practice of medicine, they can either directly employ the acquired physician, or own an operating LLC that does so. Further, an acquiring practice can directly employ the acquired physicians. The rub comes when lay companies like MSOs are purchasing non-clinical assets. Because MSOs cannot own medical practices, the transactions involving their relationships with medical practices are often fraught with peril. In short, don’t try this at home.

Key Advantages of Chapter 12 Bankruptcy for Struggling Family Farmers

By: James C. Lanik and Jennifer B. Lyday

American family farmers and family fishermen Display footnote number:1 are not immune to the effects of the current condition of the general economy. A recent industry analysis indicates that the three most pressing concerns of respondents surveyed in September 2022 were: 1) higher input costs; 2) rising interest rates; and 3) availability of inputs. Display footnote number:2 These factors are squeezing family farmers from all sides.

Needed inputs, such as fertilizer, feed, seed, etc., are becoming more expensive, if they can be had at all. At the same time, the capital needed to purchase those inputs is becoming more expensive to obtain. These trends, along with the ever-present issue of weather, may lead more farmers to seek out bankruptcy protection to maintain their livelihoods and, in some cases, to hold on to land that may have been in their families for generations.

Congress created a specialized chapter of bankruptcy—Chapter 12—in the 1980s to help struggling farmers reorganize their businesses and their debts. Display footnote number:3 A Chapter 12 bankruptcy has similarities to both a Chapter 11 reorganization and a Chapter 13 case, but significant and important differences exist between the chapters. This article provides a brief overview of some of the more material differences.

Eligibility

Chapter 12 was designed to provide farmers a structure to reorganize their business and continue to pay their debts. Thus, only certain individuals and entities can file under Chapter 12. Section 109 of the Bankruptcy Code Display footnote number:4 provides that only a farmer with regular annual income may be a debtor under Chapter 12. A farmer who exceeds the debt threshold or otherwise cannot meet the Chapter 12 requirements can still file under Chapter 11.

A “family farmer” is defined in Section 101(18) of the Bankruptcy Code as an individual or individual and spouse engaged in a farming operation:
 

  • With total debts (secured and unsecured) that do not exceed $11,097,350;
  • With at least 50 percent of the total debts that are fixed in amount (exclusive of debt for the debtor’s principal residence unless the debts arise out of a farming operation) arising out of a farming operation; and
  • Receiving more than 50 percent of the gross income of the individual or the individual and spouse for the preceding tax year, and for each of the second and third prior tax years, from the farming operation.


A “family fisherman” is defined in Section 101 (19A) and Section 109 as an individual or individual and spouse engaged in a commercial fishing operation:

  • With total debts (secured and unsecured) that do not exceed $2,268,500;
  • With at least 80 percent of total debts that are in a fixed amount arising out of a commercial fishing operation; and
  • Who receives more than 50 percent of the gross income of the individual or the individual and spouse for the preceding tax year from the operation.


A corporation may also qualify to be a Chapter 12 debtor. Section 101(18B) has the following requirements for a corporate Chapter 12 debtor:
 

  • More than 50 percent the outstanding stock or equity in the corporation or partnership must be held by one family, or by one family and its relatives;
  • The family must conduct the farming or commercial fishing operation;
  • More than 80 percent of the value of the corporate or partnership assets consists of assets relating to the farming or fishing operation;
  • Total debt of the corporation or partnership must not exceed $11,097,350 (farming operation) or $2,268,550 (commercial fishing operation);
  • At least 50 percent for a farming operation or 80 percent for a fishing operation of the corporation’s or partnership’s total debts which are fixed in amount (exclusive of debt for a principal residence by a shareholder or partner unless such debt arises out of a farming or commercial fishing operation) must arise out of the farming or fishing operation; and
  • If the corporation issues stock, the stock cannot be publicly traded.


Unlike in a Chapter 11 case, the automatic stay in a Chapter 12 also extends to co-debtors on consumer debts but not to debts incurred in the ordinary course of business; this stay is identical to the co-debtor stay in a Chapter 13 case Display footnote number:5.

Lower Fees

Once the eligibility determination has been made, the first material difference for a Chapter 12 debtor is the lower fees. Filing fees are only $278 for a Chapter 12 compared to $1,738 for Chapter 11. Display footnote number:6 Also, the quarterly fees of 28 U.S.C. § 1930 do not apply in a Chapter 12 bankruptcy, and the standing trustee fees based on plan disbursements can be much lower for a Chapter 12 case than for a Chapter 11 case. Display footnote number:7

The Trustee

In every Chapter 12 bankruptcy case, a disinterested trustee is appointed. Display footnote number:8 The trustee’s duties are typically to provide additional oversight of the bankruptcy case. However, the trustee must be heard on matters pertaining to the value of property subject to a lien, confirmation of a plan, modification after confirmation, or the sale of the property of the estate. Display footnote number:9 The trustee is paid through the plan and is also paid a percentage of plan disbursements. Display footnote number:10 Periodic reports are also required in Chapter 12 plans. Display footnote number:11

The Plan

Chapter 12 plans have many significant differences to plans under Chapter 11; some benefit the farmer, but others can be more onerous. A sampling of those differences includes:

  • No exclusivity period exists under Chapter 12. The debtor is the only entity that can ever file a plan. Display footnote number:12
  • That exclusivity is offset by the quick deadlines for filing the plan. The debtor must file a plan within 90 days of the filing of the petition, while in a Chapter 11 case, no set deadline exists other than the exclusivity period. The 90-day deadline can be extended only for situations beyond the control of the debtor. Display footnote number:13
  • No disclosure statement is required, much like in Subchapter V cases.
  • With respect to how much a farmer must pay, a Chapter 12 plan more closely resembles a Chapter 13 plan. A Chapter 12 plan must, among other things: provide future earnings/ income to the trustee; pay in full all priority claims under Section 507; and if the plan classifies claims, treat all claims in a class the same. Display footnote number:14
  • A Chapter 12 plan may provide for some or all the following: designation of classes of claims; modification of the rights of secured creditors; cure of defaults; payments to unsecured creditors; assumption of unexpired leases and executory contracts; and sale or distribution of property; modification of home mortgages; and the vesting of property in the debtor at confirmation or some other time. Display footnote number:15
  • The plan can last up to three years, though the court can extend that period to no more than five years, for cause.

Plan Confirmation

Continuing with the expedited nature of a Chapter 12 case, the confirmation hearing must occur with 45 days after the debtor files the plan. Display footnote number:16 Creditors do not vote on the plan, but they do have the opportunity to object to the plan and be heard at the confirmation hearing. Display footnote number:17 At the confirmation hearing, the court must find that: Display footnote number:18
 

  • The plan complies with applicable law;
  • The plan pays any expenses or fees required to be paid prior to confirmation;
  • The debtor has proposed the plan in good faith;
  • The debtor will pay more under the plan than would be paid in a Chapter 7;
  • The plan treats secured claims by the consent of the creditor, allowing the creditor to retain its lien and paying the allowed amount of the claim, or surrendering the collateral;
  • The debtor can make all payments under, and can comply with, the plan; and
  • The debtor will pay any required domestic support obligations.


Many of these requirements also apply to Chapter 11 plan confirmation. Importantly, a Chapter 12 plan need not satisfy the absolute priority rule, as Chapter 12 does not have an analogue to Section 1129(b)(2)(B).

Tax Provisions

Many, if not most, distressed farming operations must sell property to survive. A unique and vitally important feature of Chapter 12 is the ability to reclassify what would otherwise be priority tax claims into general unsecured claims. These reclassified tax claims can be dealt with in the plan as unsecured claims Display footnote number:19 and can be discharged. Display footnote number:20

The tax must arise from the sale or other disposition of any property used in the farming operation. Display footnote number:21 Such sale or disposition must occur only before the debtor receives a discharge, whether pre- or post-petition. Display footnote number:22

Discharge

There are two types of discharges available to a Chapter 12 debtor. A debtor will receive a standard discharge if they complete all the plan payments, other than the payments to longterm secured creditors, and certify that all domestic support obligations during the case have been paid. Display footnote number:23

A debtor may also be eligible for a “hardship discharge” regardless of whether they have completed all payments. Display footnote number:24 A hardship discharge is available only to a debtor whose failure to complete plan payments is due to circumstances beyond the debtor’s control and through no fault of the debtor. In addition, creditors must have received at least as much as they would have received in a Chapter 7 liquidation case, and the debtor must be unable to modify the plan. Display footnote number:25

Conclusion

Chapter 12 provides significant advantages over Chapter 11. The lack of a disclosure statement, plan voting, and the absolute priority rule, along with lower filing and other fees, would be enough to steer farmers to Chapter 12. Adding the ability to reclassify priority tax claims related to land sales as unsecured claims, and then to discharge those claims, makes Chapter 12 the clear choice for eligible farmers.

The authors thank Diana Santos Johnson, their associate at Waldrep Wall Babcock & Bailey PLLC, for her research and drafting assistance.

1 The U.S. Bankruptcy Code defines the terms “farmer” (11 U.S.C. § 101(20)), “family farmer” (11 U.S.C. § 101(18)), “commercial fishing operation” (11 U.S.C. § 101(7A), “family fisherman” (11 U.S.C. § 101(19A)), and other terms relating to the agriculture business. For brevity, clarity, and inclusiveness, the authors use the term “farmer” to include both those engaged in farming operations as well as those engaged in commercial fishing operations, unless otherwise noted.
2 See Purdue University/CME Group Ag Economy Barometer, Purdue University Center for Commercial Agriculture, (October 4, 2022), click here.
3 The Bankruptcy Abuse Prevention and Consumer Protection Act of 2005 extended Chapter 12 to family fishermen.
4 11 U.S.C. § 101, et seq.
5 Compare 11 U.S.C. § 1201 with 11 U.S.C. § 1301.
6 28 U.S.C. § 1930(a).
7 28 U.S.C. § 586 (e)(1)(B) and 28 U.S.C. § 1930.
8 11 U.S.C. § 1202.
9 11 U.S.C. § 1202(b)(3).
10 See 11 U.S.C. § 1226(a)(2); 28 U.S.C. § 586(e)(1). The fees are 10% of the first $450,000 in disbursements, 3% of the disbursements above $450,000.
11 Fed. R. Bankr. P. 2015(b).
12 11 U.S.C. § 1221.
13 Id.
14 11 U.S.C. § 1222(a).
15 11 U.S.C. § 1222(b).
16 11 U.S.C. § 1224.
17 11 U.S.C. § 3015(f).
18 11 U.S.C. § 1225(a).
19 11 U.S.C. § 1222(a)(5).
20 11 U.S.C. § 1228(a).
21 11 U.S.C. § 1232(a).
22 Id.
23 11 U.S.C. § 1228(a).
24 11 U.S.C. § 1228(b).
25 Id.
Jennifer Lyday Receives 2022 Pro Bono Award for the Bankruptcy Section of the NCBA

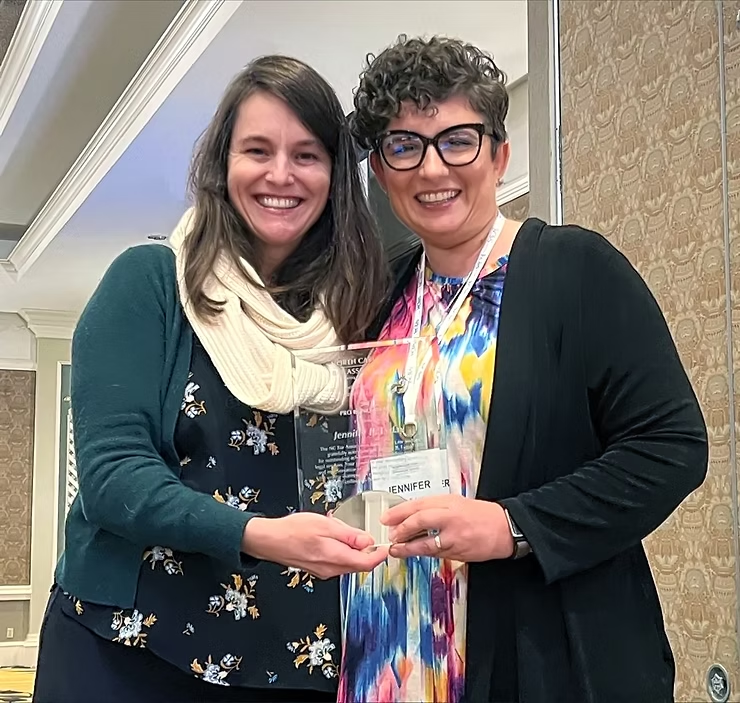
On November 11th, Jennifer Lyday, an Attorney at Waldrep Wall Babcock & Bailey PLLC, received the 2022 Pro Bono Award for the Bankruptcy Section of the North Carolina Bar Association.

Jennifer has significant pro bono experience, particularly in helping domestic violence victims obtain 50-B protection orders while working with Legal Aid of North Carolina. She has also represented parents of children abducted and taken into the U.S. in Hague Convention cases, her work on which won her the North Carolina Bar Association Young Lawyer Pro Bono Award in 2013. In those cases, she represents foreign parents whose spouses have abducted children and brought them to the U.S. She still takes such cases, which often require her to speak Spanish to her pro bono clients. She also helped a victim of religious persecution in Burma obtain asylum in the U.S. In addition, from 2016 to 2022, she served on the board of directors for The Children’s Law Center of Central North Carolina in several capacities including Chair, which provides a voice for vulnerable children in high-conflict custody and domestic violence cases by volunteering to be appointed guardian ad litem in such cases. Jennifer has also volunteered to be appointed guardian ad litem in those cases. Jennifer has also developed a partnership with Legal Aid of North Carolina’s Winston-Salem Office such that her law firm will take on certain consumer bankruptcy cases on a pro bono basis.

Jennifer volunteered her services this year for the pro bono programs offered in the Middle District and Eastern District Bankruptcy Courts. The pro bono programs provide a volunteer attorney to assist certain unrepresented parties that are unable to employ an attorney on their own behalf (pro se) with adversary proceedings and certain contested matters.

On Friday, March 4, 2022, Jennifer participated in the 4ALL Statewide Service Day, an annual call-a-lawyer pro bono program that engages volunteer attorneys to provide free legal information to thousands of North Carolinians, from the mountains to the coast. 4ALL is the North Carolina Bar Foundation’s largest annual pro bono program. Jennifer volunteered to provide advice, information, and resources to callers seeking information regarding North Carolina-related legal matters.

Earlier this year, Jennifer assisted First Church of God in Christ in Winston-Salem in stopping the foreclosure of their church. They have owned their worship space property, which contains a building valued at almost $1 million, for 23 years. Like most commercial real estate owners, First Church had a five-year term on the loan that was secured by their church property. When the term ended in February 2022, the lender was not willing to work with First Church to extend the term or give them additional time to refinance the loan, despite having an excellent payment history and substantial equity in the property. Within a few months of the term due date, the lender filed a foreclosure action in Forsyth County. First Church initially contacted Jennifer to explore the possibility of filing bankruptcy to stop the foreclosure action. After determining that bankruptcy would not be the right fit in this situation and would be too costly, Jennifer and Diana Johnson (an Associate at Jennifer’s firm), along with the firm’s bankruptcy team, decided to assist the church pro bono to delay the foreclosure action long enough for First Church to find another lender to refinance the loan. Jennifer also assisted First Church in submitting documents to the new lender and in explaining the new loan terms. Eventually, First Church was able to secure a ten-year term with a new lender and was able to obtain additional funds to replace their existing air conditioning units. Jennifer also assisted in coordinating with attorney Patti Dobbins, of Patti D Dobbins Attorney at Law, PLLC, to do the refinance loan closing pro bono. Attorney Dobbins coordinated a closing date that was flexible for the First Church board, prepared the necessary closing documents, and filed all the necessary paperwork to complete the refinance. First Church was able to close on the new loan on August 25, 2022. After the new loan closed, the foreclosure action was dismissed, and First Church was no longer at risk of losing their church home of over 20 years. First Church Pastor Bernie Cundiff stated, “Jennifer, Diana, and the team at Waldrep Wall Babcock & Bailey PLLC went the extra mile for us. They helped us every step of the way with excellence, and it was truly ‘The Hand of the Lord’!” Lisa Lash, First Church Secretary, stated, “We have been extremely blessed to have worked with such an extraordinary team! Jennifer and Diana were truly engaged in every phase of the process. Equipped with all the knowledge necessary to complete a case such as ours, they guided us with professionalism and confidence – always there to support us with an eagerness to see us succeed. We will forever be grateful for their diligence, work ethic, and their sincere compassion for our church.”

In addition to her legal, professional pro bono volunteer services, Jennifer has served as Parish Council since 2019 for the church she attends, Holy Cross Orthodox Church, in Kernersville, North Carolina.

Jennifer also manages and coordinates all of the pro bono efforts at her law firm, and strongly encourages and supports the pro bono efforts of all of the firm’s attorneys.

Several WWBB Attorneys To Speak at the 45th Annual Bankruptcy Institute

Waldrep Wall Babcock & Bailey PLLC Attorneys Jim Lanik, Ciara L. Rogers, and Jennifer B. Lyday will be speaking at the 45th Annual Bankruptcy Institute held this year at the Grandover Resort in Greensboro, North Carolina November 11-12. This year’s Bankruptcy Institute features a wide array of current and developing issues facing North Carolina bankruptcy practitioners. Our firm’s attorneys will be speaking on the following topics:

“Chapter 5 Actions and Bankruptcy Litigation,” Jim Lanik

Complex and important litigation frequently arises in bankruptcy cases. Such litigation is often brought by bankruptcy trustees and debtors-in-possession using the special statutory powers that the Bankruptcy Code provides. This panel shares an overview of current developments in bankruptcy litigation in North Carolina’s three federal districts.

“The Emergence of Subchapter V,” Ciara L. Rogers

With the recent increase in its availability, debtors have increasingly turned to the small business bankruptcy provisions of Subchapter V of the Bankruptcy Code. In this session, two experienced business bankruptcy practitioners discuss the increasing use of Subchapter V in bankruptcy reorganizations.

“Managing Privilege Issues in Bankruptcy,” Jennifer B. Lyday

This session addresses the unique privilege issues that arise in counseling clients contemplating bankruptcy and subsequently arise in bankruptcy cases and related bankruptcy litigation.

Jennifer Lyday to Participate in Debate About the Trendy “Texas Two Step” Mass Tort Bankruptcies

On November 9th, Jennifer Lyday of Waldrep Wall Babcock & Bailey PLLC, Shari Dwoskin and Tristan Axelrod of Brown Rudnick LLP, Jeffrey Gleit of ArentFox Schiff, and Geoffrey Miller of Dentons will debate the propriety and effectiveness of the trendy “Texas Two Step” mass tort bankruptcies.

In cases such as LTL (Johnson & Johnson), Aearo (3M), Bestwall (Georgia-Pacific) and others, major corporations have begun to offload tort liabilities into new spinoff corporations under a Texas statute and send the new entity into bankruptcy, sparing the valuable parent corporation the hassle of chapter 11 – and, some say, depriving cancer survivors, sex abuse victims and others of due compensation and a day in court.

Divisional mergers are one of the newest and most controversial strategies in chapter 11 today. The panel represents conflicting perspectives, including counsel for tort claimants, insurers, and corporate interests in some of the most high-profile engagements in chapter 11 today.

Click here for more information on tickets and attending the event.

Jennifer Lyday to Participate as a Panelist in IWIRC Insolvency Seminar

Waldrep Wall Babcock & Bailey Attorney Jennifer B. Lyday will be participating as a panelist during an exciting educational seminar with International Women’s Insolvency & Restructuring Confederation (IWIRC) Western Canada, IWIRC Delaware and IWIRC Carolinas to discuss the similarities and differences between the U.S. and Canadian insolvency regimes. It will be a great event to build connections with IWIRC members from across Canada and the U.S.

WHEN: Tuesday, October 25, 2022

2:00pm to 3:30pm EST

The distinguished panelists include Michelle Grant (PwC), Stephanie Wanke (Thomson Reuters), Jennifer Lyday (Waldrep Wall Babcock & Bailey PLLC) and Amanda Steele (Richards, Layton & Finger, P.A.), moderated by Stacey Greenbaum (Deloitte).

For information on this event or to register, click here.

Tom Waldrep to Participate as a Panelist in the “Hot Topics in Bankruptcy 2022″ in Chicago

Attorney Tom Waldrep is participating as a panelist in the “Hot Topics in Bankruptcy 2022” in Chicago sponsored by Turnaround Management Association (TMA) on Wednesday, September 21, 2022. TMA’s nationally renowned panelists will provide thoughts and analysis from the front lines on recent developments in bankruptcy practice, including addressing the “Texas-Two Step”, third party releases, and the prevalence of independent directors addressing the complex conflict issues that continue to arise in the restructuring world.

Attorney Jim Wall Quoted in Medscape Medical News Article

Waldrep Wall Babcock & Bailey PLLC Attorney Jim Wall was quoted in a Medscape Medical News Article published in August 2022, “Should You Sell Your Practice to a Private Equity Firm?,” written by Leigh Page.

Read Article

Medscape is the leading online global destination for physicians and healthcare professionals worldwide, offering the latest medical news and expert perspectives; essential point-of-care drug and disease information; and relevant professional education and CME.

Should You Sell Your Practice to a Private Equity Firm? – Medscape – Aug 11, 2022.