Partner Tom Waldrep is Cited in Bloomberg Law Article

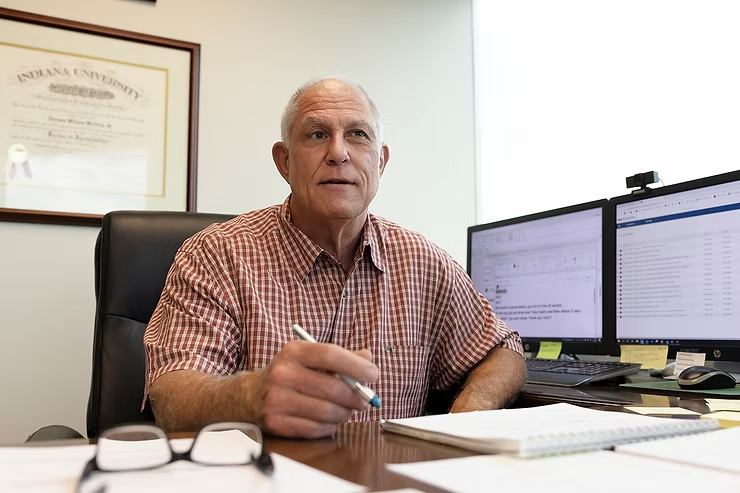
Waldrep Wall Babcock & Bailey PLLC Partner Tom Waldrep was recently cited in an article in Bloomberg Law published July 31, 2023, “Litigation Funders See Growing Opportunities in Bankruptcy Boom.”

The article discussed how litigation finance is working its way into corporate bankruptcy proceedings as Chapter 11 cases pile up, enabling more lawsuits and strengthening plaintiffs’ claims against third parties who may have caused or worsened a bankrupt company’s distress.

The article goes on to mention:

“This year, the trustee for a group of bankrupt rural hospitals across the South and Midwest took on a third-party investment to fund claims accusing the hospitals’ former owners and managers of using the companies to perpetuate a fraudulent insurer billing scheme. Trustee Thomas W. Waldrep Jr. in June won approval from a North Carolina bankruptcy court to bring in Omni Bridgeway Ltd. to finance the suit.

Carmel, who helped Waldrep secure the financing, said he thinks bankruptcy practitioners have become more familiar with litigation funding than they were just a few years ago. Although it’s not the right fit for every bankruptcy case, litigation funding allows trustees “to pursue more litigation that they might not have pursued to begin with,” he said.

In many situations, that outside funding “reduces the pressure of taking an early settlement,” said Carmel.”

Click here to read the entire article.

Problems in the Code: Oversight Results in Uncertainty for Small Business Owners Converting to Subchapter V.

By: Jennifer B. Lyday and Josh Plummer

In February 2020, Congress codified the Small Business Reorganization Act of 2019 (SBRA) as subchapter V of chapter 11 of the Bankruptcy Code.1 In doing so, Congress established a relative safe haven for eligible small businesses that provides a more streamlined and less costly chapter 11 relief process.2

However, in its haste to “permit qualifying small business debtors to file [for] bankruptcy in a timely, cost-effective manner,”3 Congress seemingly failed to amend § 348 (b) — a critical Code section that grants timeline extensions in most instances when cases are converted from one chapter to another.4 As a result, many small businesses converting their cases to subchapter V quickly find themselves mired in a purgatory of rapidly expiring deadlines and additional litigation, with no consensus on a solution.5 Whether Congress’s omission regarding § 348 (b) is by oversight or intent,6 the recommended solution remains the same: Congress must amend § 348 (b) to allow for extensions in subchapter V conversion cases, as they already do with other chapter 11 conversions, to provide judicial clarity and meet the SBRA’s intent.

Section 348

Section 348 provides clarity regarding the “effects of conversion” on a debtor’s case. Debtors often convert their bankruptcy cases to different chapters of the Bankruptcy Code for various reasons, including unforeseen ineligibility under the original chapter filing or changed circumstances.7 However, while converting a case to another chapter may be necessary or beneficial to the debtor, conversions present several new complexities. For example, conversions often result in shifting rules regarding the property that makes up the estate, and the passage of time prior to the conversion frequently conflicts with filing deadlines under the new chapter. Section 348 anticipates these issues and provides statutory remedies for most of them.

Section 348 (f) (1) (A) clarifies what property makes up the estate in cases converted from chapter 13 to another chapter.8 In addition, § 348 (b) addresses expired — or rapidly expiring — filing deadlines under enumerated sections that arise when debtors convert to a new chapter.9 For example, § 1121 (b) provides that under a chapter 11 case, “only the debtor may file a plan until 120 days after the date of the order for relief under this chapter” to file a plan.10 After a debtor converts their case to chapter 11, confusion is likely to ensue over when the 120-day deadline to file a new plan began. Was it the date that the order for relief under the original chapter was granted, or the date of conversion? If the former, this could be particularly stressful for a debtor when a substantial amount of time has passed since the original filing, and a filing deadline under the new chapter is either looming or lapsed.

Luckily, § 348 (b) provides a cogent solution to this common issue. To resolve the possible ambiguity, § 348 (b) provides that in cases that have been converted under §§ 706, 1112, 1208 or 1307, “the order for relief under this chapter” in § 1112 (b) — and 12 other enumerated sections of chapters 7, 11, 12 and 13 — “means the conversion of such case to such chapter.”11 Thus, in effect, § 348 (b) grants automatic extensions to debtors under these enumerated sections by “resetting the clock” for filing deadlines to the date of conversion.

The Omission

Unfortunately, when Congress codified the SBRA, it did not amend § 348 (b) to incorporate the sections of subchapter V containing deadlines.12 For example, § 1189, which provides for a 90-day deadline for debtors to file a plan under subchapter V, is not incorporated in § 348 (b). As a result, after converting to subchapter V proceedings, small business debtors are not eligible for the same “extension” to file a plan under § 1189 that § 348 (b) automatically grants under § 1121 (b) for debtors who convert to chapter 11. Instead, they find themselves immediately scrambling to file for an extension before the 90-day deadline lapses, if it has not already.13

Although the requirement for additional litigation to attain an extension is not an insurmountable death knell,14 at a minimum it frustrates Congress’s intent for a streamlined and cost-effective proceeding for qualified small businesses.15 This frustration is amplified by the fact that the additional litigation would be wholly unnecessary if a debtor had converted the case to a general, non-small-business-friendly chapter 11 proceeding, and so is only necessary due to Congress’s failure to amend § 348 (b) when codifying the SBRA.

How Courts Have Dealt with the Omission

Although only a handful of courts have issued opinions on a debtor’s request for extensions under § 1189 after converting to subchapter V, the disparate results of those courts underscore the urgency of the issue at hand.16 One court adopted a strict interpretation and held that debtors immediately placed themselves in default of § 1189 (b) when they elected to convert to subchapter V, claiming that “Congress purposefully set a short deadline for a debtor to file a plan” and “set a very high standard for an extension of that deadline.”17

Another court held that a “court may extend deadlines in § 1189 even after the periods have lapsed” when the need for the extension is “due to circumstances for which the debtor should not justly be held accountable.”18 However, the judge in that case went on to deny the requested extension because numerous delays were “fully within the debtor’s control,” before offering limited consolation that his ruling was not fatal to the debtor’s case because “a late-filed plan [does not] doom a subchapter V case.”19

In another case, which cited both aforementioned cases, the court noted that no courts “have articulated any kind of step-by-step basis upon which to evaluate motions to convert filed after deadlines … have passed” before establishing its own “evaluative device.”20 Although the court’s analysis is coherent, metered and fair — and arguably debtor-friendly — its complex evaluation also provides the best possible illustration for understanding the necessity for Congress to amend § 348 (b) to incorporate §§ 1188 and 1189.21 The court started with an analysis of whether conversion was appropriate under § 1307 (d) — the chapter in which the debtor initially filed — before moving on to the question of whether conversion or immediate dismissal was proper in the new chapter under § 1112 (b).22

Before deciding on § 1112 (b), the court engaged in a circular analysis by first ensuring that the debtor did not run afoul of § 1189 to confirm that § 1112 (b) (4) (j) was not triggered.23 Next, after determining whether conversion was proper, the court finally engaged in evaluating the request for extension, but noted that the extension request must be made by a separate motion, and still left open the possibility that the extension request may be denied by the court for cause, fault or other bad faith.24

The Practical Effect of an Overly Complicated Judicial Analysis

Although the Keffer court provides an effective analysis that may offer the best option for courts evaluating these cases in the future, it should be noted that the resulting “evaluative device” is overly complex and inconsistent with the principles of judicial efficiency and consistency.25 In fact, some debtors might even hesitate to convert to the streamlined subchapter V proceeding designed specifically for them due to this uncertainty of outcome.26 Moreover, the litigious framework made necessary by the omission of subchapter V intent regarding subchapter V. While denial of a § 1189 extension following conversion might not be fatal to a debtor’s case per se, debtors are nonetheless required to litigate the same things multiple times, which results in additional filings, time and costs.27 This runs in direct contradiction to Congress’s noted intent for subchapter V to “permit qualifying small business debtors to file [for] bankruptcy in a timely, cost-effective manner.”28

Even the Keffer court noted that “it would have been helpful for Congress to [have provided] some guidance with respect to conversion from other bankruptcy chapters” before arriving at the conclusion that “it is up to the courts to interpret those laws” as best they can when unforeseen circumstances require debtors to convert their proceedings midstream.29 In Trepetin, the court noted that Congress expressed “significant concern for small business debtors, wanting to provide them with a realistic option for reorganizing and saving their business operations” that “balance [d] the … goals of speed and access.”30 Thus, it stands to reason that Congress did not intend the current result where debtors face the prospect of potential denial of conversion to subchapter V or, at best, the prohibitively expensive purgatory of additional litigation necessitated by compulsory extensions due to an unanticipated conversion.

The Recommendation

As the Keffer court noted, “[s] ubchapter V is a valuable tool for qualifying debtors and will facilitate reorganizations that were not possible before.”31 However, it is not a valuable tool for small business owners when a small oversight in the process of statutory amendment leaves them in a purgatory of uncertainty, time and cost. Therefore, consistent with congressional intent for the SBRA and in the interests of judicial efficiency, it is imperative that Congress amend § 348 (b) to incorporate the relevant sections from subchapter V conversion cases as they already do with all other chapter 11 conversions.

1 See Small Bus. Reorganization Act of 2019, Pub. L. No. 116-54, 133 Stat. 1079.
2 In re Thurmon, 625 B.R. 417, 419 (Bankr. W.D. Mo. 2020).
3 In re Keffer, 628 B.R. 897, 905 (Bankr. S.D. W.Va. 2021) (quoting In re Seven Stars on the Hudson Corp., 618 B.R. 333, 339-40 (Bankr. S.D. Fla. 2020)).
4 Id.; see also 11 U.S.C. § 348 (b).
5 See generally Keffer, 628 B.R. 897; In re Seven Stars on the Hudson Corp., 618 B.R. 333; In re Trepetin, 617 B.R. 841 (Bankr. D. Md. 2020); In re Tibbens, No. 19-80964, 2021 WL 1087260 (Bankr. M.D.N.C. Mar. 19, 2021). The court in each of these cases comes to its conclusion in a different manner.
6 It is difficult to know whether Congress’s failure to amend § 348 (b) was intentional or not, but circumstantial evidence indicates that it was most likely unintentional. First, § 348 was originally drafted in 1978 and last amended in 2010 (see Pub. L. No. 95-598, 92 Stat. 2568; Pub. L. No. 111-327, 124 Stat. 3558), while the SBRA was not even drafted until 2019. Supra n.1. In addition, aside from § 348, the key language — “the order for relief under this chapter” — is only contained in 16 other sections. See §§ 701, 727, 923, 1102, 1110, 1121, 1141, 1188, 1189, 1192, 1201, 1221, 1228, 1301, 1305 and 1328. Of those 16 sections, 11 are incorporated into § 348 (b). Id.; see also § 348 (b). Of the five unincorporated sections, three of them are from the newly codified subchapter V. See §§ 1188, 1189 and 1192. This is noteworthy because all other chapter 11 sections using the key language are incorporated into § 348. See §§ 348 (b), 1102, 1110, 1121 and 1141. Thus, to find that Congress’s omission was intentional, one would have to assume that Congress intended to incorporate all other relevant chapter 11 sections but chose to exclude the relevant subchapter V sections. The more plausible explanation is that Congress simply failed to account for amending § 348 when it created subchapter V with the SBRA.
7 Supra n.5.
8 11 U.S.C. § 348 (f) (1) (A).
9 See 11 U.S.C. § 348 (b) (“Unless the court for cause orders otherwise, in sections 701 (a), 727 (a) (10), 727 (b), 1102 (a), 1110 (a) (1), 1121 (b), 1121 (c), 1141 (d) (4), 1201 (a), 1221, 1228 (a), 1301 (a), and 1305 (a) of this title, “the order for relief under this chapter” in a chapter to which a case has been converted under section 706, 1112, 1208, or 1307 of this title means the conversion of such case to such chapter.”).
10 11 U.S.C. § 1121 (b) (emphasis added).
11 11 U.S.C. § 348 (b).
12 Id.; see also 11 U.S.C. § 1189.
13 See, e.g., In re Keffer, 628 B.R. at 899.
14 See In re Tibbens, 2021 WL 1087260, at *6 (stating that Congress did not intend to have late-filed plan doom subchapter V case).
15 Keffer, supra n.3.
16 Supra n.5.
17 In re Seven Stars on the Hudson Corp., 618 B.R. at 338-39, 345.
18 In re Tibbens, 2021 WL 1087260, at *8.
19 Id. at *6, *9.
20 In re Keffer, 628 B.R. at 909.
21 Id.
22 Id.
23 Id. Section 1112 (b) (4) (j) states that “failure to … file or confirm a plan, within the time fixed by this title,” is grounds for “cause” to dismiss under § 1112 (b) (1), thus a debtor requesting conversion after the expiration of the 90-day timeline to file a plan under § 1189 might automatically qualify for dismissal. However, the court reasoned that as long as the grounds for the requested extension are “attributable to circumstances for which the debtor should not justly be held accountable” per § 1189, § 1112 (b) (4) (j) is not triggered, and conversion — rather than dismissal — is proper.
24 Id.; see also In re Tibbens, 2021 WL 1087260, at *9 (declining to extend deadlines, stating that numerous delays “occurred in the administration of the chapter 13 case that were fully within the debtor’s control and for which he should be held accountable”).
25 In re Keffer, 628 B.R. at 909; see also In re Seven Stars on the Hudson Corp., 618 B.R. 333; In re Trepetin, 617 B.R. 841; In re Tibbens, No. 19-80964, 2021 WL 1087260 (noting disparate analyses and outcomes in various jurisdictions).
26 Id.
27 In re Keffer, 628 B.R. at 909 (noting that Keffer court framework requires that appropriateness of conversion be evaluated under two different chapters and § 1189 be litigated at two different steps in framework, with second final, dispositive § 1189 analysis requiring separate motion).
28 Id. at 905 (quoting In re Seven Stars on the Hudson Corp., 618 B.R. at 339-40).
29 In re Keffer, 628 B.R. at 910; see also In re Tibbens, 2021 WL 1087260, at *4. In Keffer, the debtor did not know they could not file under chapter 13 until after the Internal Revenue Service processed their tax returns, while the debtor in Tibbens had to convert from chapter 13 because they discovered that they exceeded the debt limitations of chapter 13 cases after filing.
30 In re Trepetin, 617 B.R. at 846-47 (emphasis added).
31 In re Keffer, 628 B.R. at 910.
Jennifer Lyday & Diana Santos Johnson Present at the ABI Southeastern Bankruptcy Institute Workshop

pro bono lawyer

Attorneys Jennifer Lyday and Diana Santos Johnson attended and presented at the American Bankruptcy Institute (ABI) 2023 Southeastern Bankruptcy Workshop on July 20-21 at The Ritz-Carlton in Amelia Island, Florida.

Jennifer presented on, “From Johns-Manville to LTL (and Beyond?): Do Mass-Tort Bankruptcies Have a Future – and Should They?” and Diana presented on presentation, “Consumer Session: Conversions in Chapters 13 and 7.”

Thanks for representing our firm!

Tips For Preparing Your Practice For Sale

By: James D. Wall, Esq.

If you are contemplating a sale of your practice, you should thoughtfully consider the issues raised below. Selling a practice is in some respects like selling a house:  that is, you wouldn’t sell your house without first making sure the house presents well to potential buyers. The same is true for a professional practice.
 

Tip One:  Corporate Hygiene

You should review corporate charter documents to make sure you have conducted your business as originally authorized. Further, you should make sure that your practice is registered with the applicable licensing board. If there have been any internal changes of ownership, those should have been reported to the licensure board. You should also review your practice’s minutes to make sure those comply with state law.
 

Tip Two:  Employment Review

You should review (or have someone review) the employment agreements of all the providers and key employees of the practice. Can the employment agreements be assigned? If a contract is silent on assignability, then it is generally considered to be assignable. Does a “change of control” provision trigger an employee’s right to terminate the agreement. Further, you should review in employees’ contracts any restrictive covenants regarding competition. North Carolina courts have interpreted a transaction to trigger the commencement of the post-employment restrictive term. That is, if the covenant prohibits competition for one year after employment ends, some courts have concluded that the period commences to run as of the date of a transaction pursuant to which the employer is sold. You should also confirm that all of your licensed providers are current with respect to license renewals.
 

Tip Three:  Review of Third-Party Payor Agreements 

Many third-party payor agreements restrict assignment. Thus, it is highly unlikely that provider agreements would be assignable. Upon a transaction, providers often need to be recredentialed, which of course takes time. Some third-party payors require prior written notice to any type of change in ownership.
 

Tip Four:  Evaluate Third-Party Vendor Contracts 

The same type of analysis must be done with respect to third-party vendors. The contracts of primary concern are leases of your office space and equipment. These contracts typically do not allow assignment without permission from the lessor. If permission is required, that needs to be noted prior to sale so that the acquiring entity can continue with respect to office space and significant equipment. Institutional lessors often need quite a bit of time to agree to an assignment.
 

Tip Five:  Financial Information

You will want to meet with your accountant to make sure that you have financial reports up to date and in order for the previous three years. You should be able to explain any unusual peaks or valleys in profits, and any significant balance sheet items. If you received money as a result of the pandemic, you should have documents regarding your application for funds as well as the forgiveness of any loans due.
 

Tip Six:  Consider Type of Sale

You should also consider the ramifications of selling stock or assets. In our state, a medical practice must be owned by physicians (there are certain exceptions with respect to physicians owning practices with other health professionals, such as optometrists, psychologists, and APPs). Nonetheless, an unlicensed third party will not be able to purchase the stock of your practice.
 

A management services organization (referred to as an MSO) can purchase certain assets of your practice, but a licensee must own a medical practice. An MSO makes its money by managing the non-clinical affairs of the practice for a fee. The MSO often embraces a “friendly physician model” wherein the practice continues to be owned by a physician who would be “friendly” to the MSO and enter into a long-term management agreement with the MSO.
 

You need to discuss with your tax advisor the ramifications of an asset sale and a stock sale before you enter into a letter of intent with a prospective purchaser. Purchasers typically like to buy assets because this structure is more likely to extinguish prior claims against the practice. Sellers often favor sales of stock or membership interests because of favorable tax treatment.
 

Tip Seven:  Review Policies

Buyers active in the health care space will want to review significant policies of the practice in their due diligence. In this regard, you should make sure that HIPAA and other policies are up to date and are being followed. It is not uncommon for practices to have very well drafted policies, but very few in the practice know of their existence.
 

Tip Eight:  Fine-Tuning EBITDA

If you have a time horizon that will permit some planning, you will want to use that opportunity to maximize EBITDA. EBITDA is an acronym for “Earnings Before Interest, Taxes, Depreciation and Amortization.” Many transactions will be priced at a multiple of EBITDA. So, for every dollar that is created in EBITDA, purchase price will be increased by the multiple. For example, if the multiple is six times EBITDA, one dollar in EBITDA results in six dollars of purchase price. Typically, purchasers will look at a trailing 12 to 24 month calculation of EBITDA to determine purchase price. While these calculations routinely exclude extraordinary items, there may be opportunities within the practice to save money, thereby increasing purchase price. Also, in a professional practice, salaries of the owners are often normalized using national data, and then the excess is added to EBITDA. So, for example, if a doctor is making $350,000 in his or her own practice, and the national data suggests that earnings should be $280,000, the $70,000 is added back to earnings.
 

Tip Nine:  Be Ready to Commit Post-Sale Employment

The purchase price can be significantly affected by the sellers’ willingness to stay around post-sale as employees of the newly created enterprise. If you are willing to stick around, then that often creates a higher purchase price.
 

Tip Ten:  Tell the Truth

Resist the urge to puff beyond the boundaries of truthfulness. If you try to cover up termites with plywood, the buyer will find the termites in its due diligence, and all trust will be lost.

Attorneys at Our Firm Update and Write Chapters in the 2023 NC Bankruptcy Practice Manual

Waldrep Wall Babcock & Bailey PLLC had several attorneys at our firm update and write Chapters in the North Carolina Bankruptcy Practice Manual, Ninth Edition, that was recently released.

Those chapters include:

Chapter X. Claims

Authors: Diana Santos Johnson, Pamela P. Keenan, James C. Lanik

Chapter XIX. Subchapter V Small Business Reorganization

Authors: Jennifer B. Lyday, Melanie J. Raubach, Ciara L. Rogers

With a focus on procedural and substantive nuances, the newly released North Carolina Bankruptcy Practice Manual, Ninth Edition, provides valuable and thorough analysis of legal issues common to bankruptcy cases, as well as additional insight, expertise, and background on issues particular to practicing bankruptcy law in North Carolina. This comprehensive publication includes pertinent case law developments, discussion of essential practices and procedures, updates to Bankruptcy Rules and local bankruptcy rules, and over 180 essential bankruptcy forms, plus a brand-new chapter examining Subchapter V small business reorganization.

Click here to learn more and get your copy.

Children’s Law Center of Central North Carolina Presents at Waldrep Wall Babcock & Bailey PLLC

Iris Sunshine, Executive Director of the Children’s Law Center of Central North Carolina, came to Waldrep Wall Babcock & Bailey PLLC today to present on the mission and goals of The Children’s Law Center (CLC), which provides a voice for vulnerable children in court proceedings and advocates for their best interests including safe placement and counseling in CH 50B Civil Domestic Violence cases (DVPO) and CH 50 High Conflict Custody cases.

Our firm is honored to support The Children’s Law Center and participate as a Voice Sponsor with their 2023 “Speak up for Children” event this coming October!

Attorney Jennifer B. Lyday Joins Winston-Salem Symphony Board of Directors

Waldrep Wall Babcock & Bailey PLLC Attorney Jennifer B. Lyday recently joined the Winston-Salem Symphony Board of Directors. She will be serving on the Board through 2026.

During the past 75 years, the Winston-Salem Symphony has grown into a nationally recognized regional orchestra employing 75 professional musicians on a per-service basis. Currently, the full orchestra performs 35-40 concerts per year. The Symphony also boasts a 120-voice volunteer Chorus and an inspiring music education program including in-school ensemble programs, young people’s concerts, an Academy for young students, and a Youth Orchestras program consisting of three youth orchestras. Education programs produce over 28,000 student encounters annually.

For more information about the Winston-Salem Symphony, please visit https://www.wssymphony.org/.

Jennifer B. Lyday Co-authors Article for ABI Journal

pro bono lawyer

The June 2023 issue of the American Bankruptcy Institute Journal featured an article written by Waldrep Wall Babcock & Bailey PLLC Partner Jennifer B. Lyday and Josh Plummer, our 2022 Summer Associate, “Problems in the Code: Oversight Results in Uncertainty for Small Business Owners Converting to Subchapter V.

Click here to read the article.

The American Bankruptcy Institute is a multi-disciplinary, non­partisan organization devoted to bankruptcy issues. ABI has more than 12,000 members, representing all facets of the insol­vency field.

Chambers USA 2023 Rankings Released

Chambers USA released their 2023 rankings today, and Waldrep Wall Babcock & Bailey PLLC is happy to announce that Partners Tom Waldrep, Jennifer Lyday, and Kevin Sink are ranked, along with our Bankruptcy/Restructuring Practice Area.

Chambers USA is the world’s leading legal data and analytics provider, highlighting the top lawyers and law firms across the USA for over two decades, so that buyers of legal services are equipped to make the best choice for when it matters. Their legal rankings are unrivaled in accuracy, depth and quality and are conducted by their dedicated team of independent researchers, ensuring that their outcomes are trusted and credible across the globe.

Bankruptcy: Your Friend During Tough Financial Times

By: Diana Santos Johnson

Typically, you do not think of bankruptcy as something that can empower and elevate individuals. However, as we enter 2023 with the nonstop news of record-breaking inflation and a possible recession, bankruptcy can be exactly this. During these times, it is important to remember that bankruptcy is a solution for some individuals struggling with their current finances.1

Bankruptcy exists to give the “honest but unfortunate debtor”2 a fresh start, but many are unaware of how bankruptcy can actually benefit individuals. This article will briefly explain how bankruptcy can assist individuals, what situations a bankruptcy filing will have the most impact on, and the qualities to look for in a bankruptcy attorney.

Chapters 7 and 13 Bankruptcies

There are several types of bankruptcies – Chapters 7, 9, 11, 12, 13, 15 – but the two that primarily assist individuals and married couples – referred to as “debtors” – are Chapter 7 and Chapter 13.

Chapter 7 bankruptcies are liquidation” bankruptcies and generally eliminate debt without a repayment plan. In this chapter,  a bankruptcy trustee is appointed to sell the debtor’s nonexempt assets and distribute the sale proceeds to creditors under the provisions of the Bankruptcy Code. The Bankruptcy Code does allow the debtor to keep specific “exempt” property. This is the debtor’s real and personal property that is protected by state or federal law, such as equity in a home and vehicle, that the bankruptcy trustee cannot sell. If the exemption statutes do not protect property, the bankruptcy trustee will liquidate, or sell, the debtor’s remaining assets. In most Chapter 7 cases, all the debtor’s property will be protected, and the bankruptcy trustee cannot sell it. However, potential debtors should note that filing a petition under Chapter 7 may result in property loss. Unfortunately, a Chapter 7 bankruptcy is only available to those who pass the means test.3 The means test is a calculation that considers several factors, including your income, expenses, and family size, to determine whether you have enough disposable income to repay your debts. If your income is below the state median, you pass the means test and can move forward with a Chapter 7 bankruptcy. If you meet the filing requirements of Chapter 7, once your case is over, your debts will be discharged, or in other words, eliminated. If the debt is secured by collateral, such as a mortgage or car, you must continue to make payments to keep these items or release them in your Chapter 7.4

Chapter 13 bankruptcies are “wage earners” bankruptcies because you must have regular income to repay some of your debts. This chapter allows debtors to repay some or all their debts in a three-to-five-year period. Chapter 13 debtors present a plan on how they will repay their debts. Not all debts get repaid, and the amount of your plan payment depends on various factors, including the arrears on certain obligations and the value of the collateral. Payments are made monthly to a Chapter 13 Trustee who distributes payments to your creditors. At the end of your plan, you will be current on your mortgage and could have your vehicle paid off. Any unsecured debts like credit cards, personal loans, or medical bills not paid in full during the Chapter 13 plan will get discharged. A Chapter 13 plan also allows you to keep any property that may not be “exempt” by paying the equity into the Chapter 13 plan. You also do not have to pass a means test in a Chapter 13 bankruptcy. Instead, you will need to pay any additional income into your Chapter 13 plan payment if you have disposable income.5

Where Bankruptcy Can Make a Difference

Bankruptcy is not the solution to all financial problems but it can improve certain situations. If you encounter individuals with the following financial dilemmas, bankruptcy may be an option that can assist them:
 

  • Medical debt. A bankruptcy discharge usually eliminates medical debt. Despite the passage of the Affordable Care Act in 2010, medical debt remains one of the top reasons that individuals file bankruptcy.6
  • Credit cards. A bankruptcy discharge typically eliminates credit card debt. Recent news suggests that Americans now carry more credit card debt because of higher prices due to inflation.7
  • Foreclosures. If you are facing a foreclosure of your home or even a rental property, a Chapter 13 bankruptcy can help you set up a payment plan to get current. Alternatively, a Chapter 7 bankruptcy can help you walk away from the home by eliminating any deficiencies you may owe.
  • Repossessions. If you are behind on your car payments or your car gets repossessed, bankruptcy can help you keep or retrieve your vehicle. A Chapter 13 bankruptcy will help you repay the amount you are behind on or even lower your payments, depending on how long you have owned the vehicle. If you no longer want to keep your car, a Chapter 7 can help eliminate any balance you may have owed on the car after it was sold at auction.
  • Temporary setbacks after a job loss. Many Americans live paycheck to paycheck, and a job loss will wreak havoc on personal finances. A Chapter 13 bankruptcy would allow debtors to repay mortgage payments, car payments, and other debts that may have gotten behind due to a job loss.
  • Civil lawsuits. Both Chapter 7 and Chapter 13 bankruptcy stop civil actions from moving forward through the automatic stay. The automatic stay is an injunction that stops lawsuits, foreclosures, garnishments, and all collection activity against the debtor when a bankruptcy petition is filed.8
  • Wage Garnishments. Some states allow for wage garnishments based on civil judgments. A Chapter 7 or a Chapter 13 bankruptcy will stop the wage garnishment and allow you to keep your hard-earned income. While this list is not exclusive, these are typical situations where bankruptcy can be your friend. It is important to note that while bankruptcies have eliminated student loans in some instances, a bankruptcy filing will not typically discharge student loans.9

Finding the Right Bankruptcy Attorney

Bankruptcy is a specialized area of law (there are separate bankruptcy courthouses!), and it is vital to find a knowledgeable attorney if you are considering filing bankruptcy. One of the keys to being comfortable filing bankruptcy is finding an attorney who thoroughly explains the eligibility requirements and the entire bankruptcy process to you. Look for attorneys who personally handle the consultations, especially the initial consultation.

You also want to ensure that your attorney answers all your questions about the bankruptcy process. For many, speaking with a bankruptcy attorney is the first time individuals honestly assess their entire financial picture. You want to know that the attorney is answering your questions and giving you the information you need to decide if bankruptcy is the right step for you. Many individuals are concerned about how their credit will be impacted by filing bankruptcy. An effective bankruptcy counsel will not only take this concern seriously and address the potential consequences of filing bankruptcy but can also explain what happens to your debts and your credit if you do not file bankruptcy.

Bankruptcy attorneys typically advertise their services on television or the radio. Still, another way to find a bankruptcy attorney is to talk to family members and friends who have filed bankruptcy. Ask them if they were satisfied with their bankruptcy attorney andexperience. Often, the best bankruptcy attorneys do not advertise and find new clients solely through word of mouth.

Bankruptcy exists to give individuals a fresh start. With the proper knowledge and understanding of how bankruptcy works, bankruptcy can become your friend and empower individuals to overcome their financial problems in 2023.

1 Filing bankruptcy is a decision that is made on a case-by-case basis, and this article is not intended for legal advice. If you are considering bankruptcy, please meet with a qualified bankruptcy attorney who can assist you in making this determination.
2 7 Collier on Bankruptcy ¶ 1112.07[3] (citation omitted).
3 See 11 U.S.C. § 707(b)(1)-(2).
4 This is an overview of a Chapter 7 bankruptcy. The complete statutory requirements of Chapter 7 bankruptcies can be found at 11 U.S.C. §§ 701-784.
5 This is an overview of a Chapter 13 bankruptcy. The complete statutory requirements of Chapter 13 bankruptcies can be found at 11 U.S.C. §§ 1301-1330.
6 Kimberly Amadeo, “Medical Bankruptcy and the Economy,” The Balance (January 20, 2022).
7 “Americans are piling up credit card debt — and it could prove very costly,” NPR (January 11, 2023).
8 See 11 U.S.C. § 362.
9 See NCLC Publication, New Process to Discharge Student Loans in Bankruptcy, which describes Guidance issued by the Department of Justice on how bankruptcy debtors can obtain discharges of their student loans using a ten-step process. John Rao, New Process to Discharge Student Loans in Bankruptcy, NCLC (December 12, 2022).